

Topics worth your time: a component-level teardown of DJI’s drones, the case for modernizing existing machine shops, searchable PCB designs and annotated chip die shots, understanding Schneider’s recent acquisition of PTC, and learning to read schematics.
Interesting Links
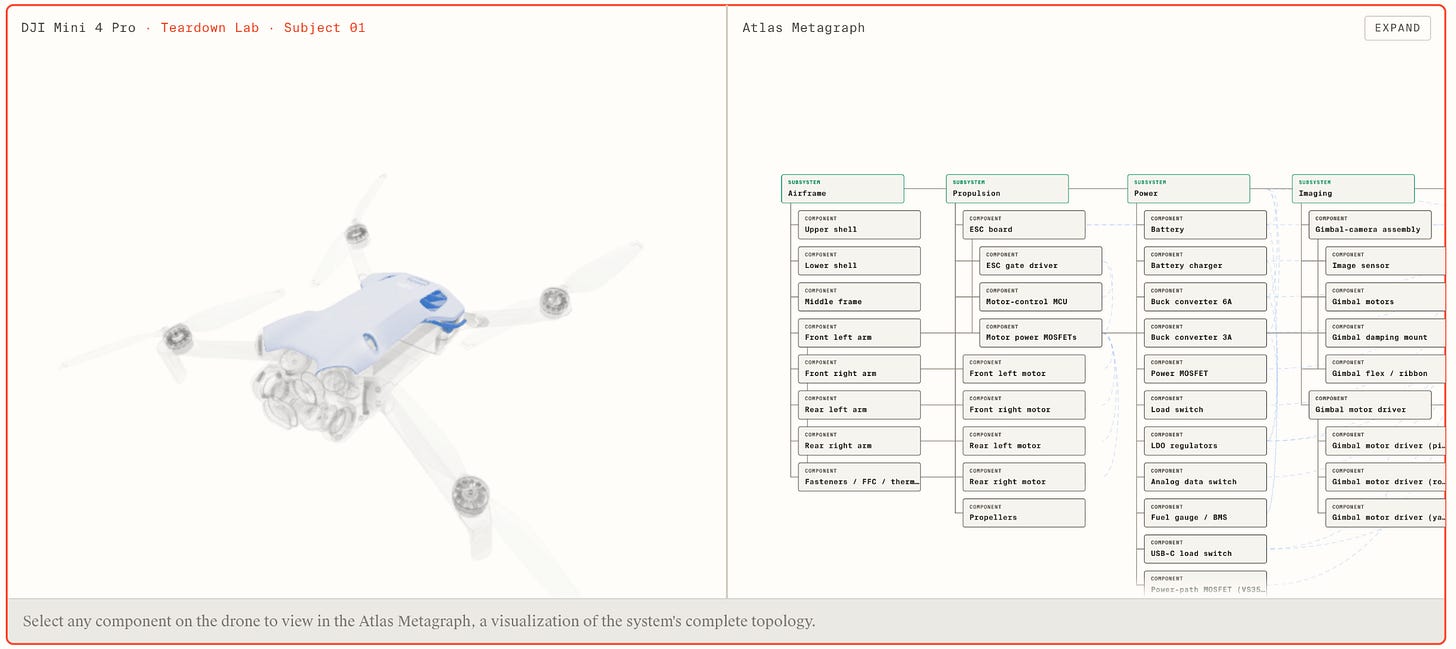
- In December of last year, the FCC added all foreign-made drones to its Covered List, effectively barring new DJI models from the U.S. market. Much like how Bambu Lab captured the desktop 3D printing market, DJI has become the default in its category: it holds ~70% of the global drone market and flies in over 90% of U.S. police and fire departments. It’s tempting to attribute both companies’ success to inherent structural advantages, but a component-level teardown of two DJI Minis reveals the specific reasons in the hardware itself. A couple notes, first on margins: DJI earns SaaS-like margins on hardware, ~79% gross margin on a $139 BOM for the Mini 4 Pro. The team estimates comparable U.S. sourced parts would cost 2-3x more, which is why U.S. drone makers mostly can’t compete in consumer markets and focus on enterprise and defense instead. Skydio met a similar fate when it exited consumer markets in 2023. Second, on strategy: DJI started as a system integrator, building OTS parts into a product to get to market fast and win share. Once volume could cover the design cost, it moved to integrate vertically to reclaim margins. For DJI, this meant collapsing discrete chips like the flight controller into a custom SoC, as well as increasing the share of in-house components from ~22% to ~44% over 4 years.
- A side note: the interactive teardown itself is a work of art - click around for the cost model or to trace the assembly topology!
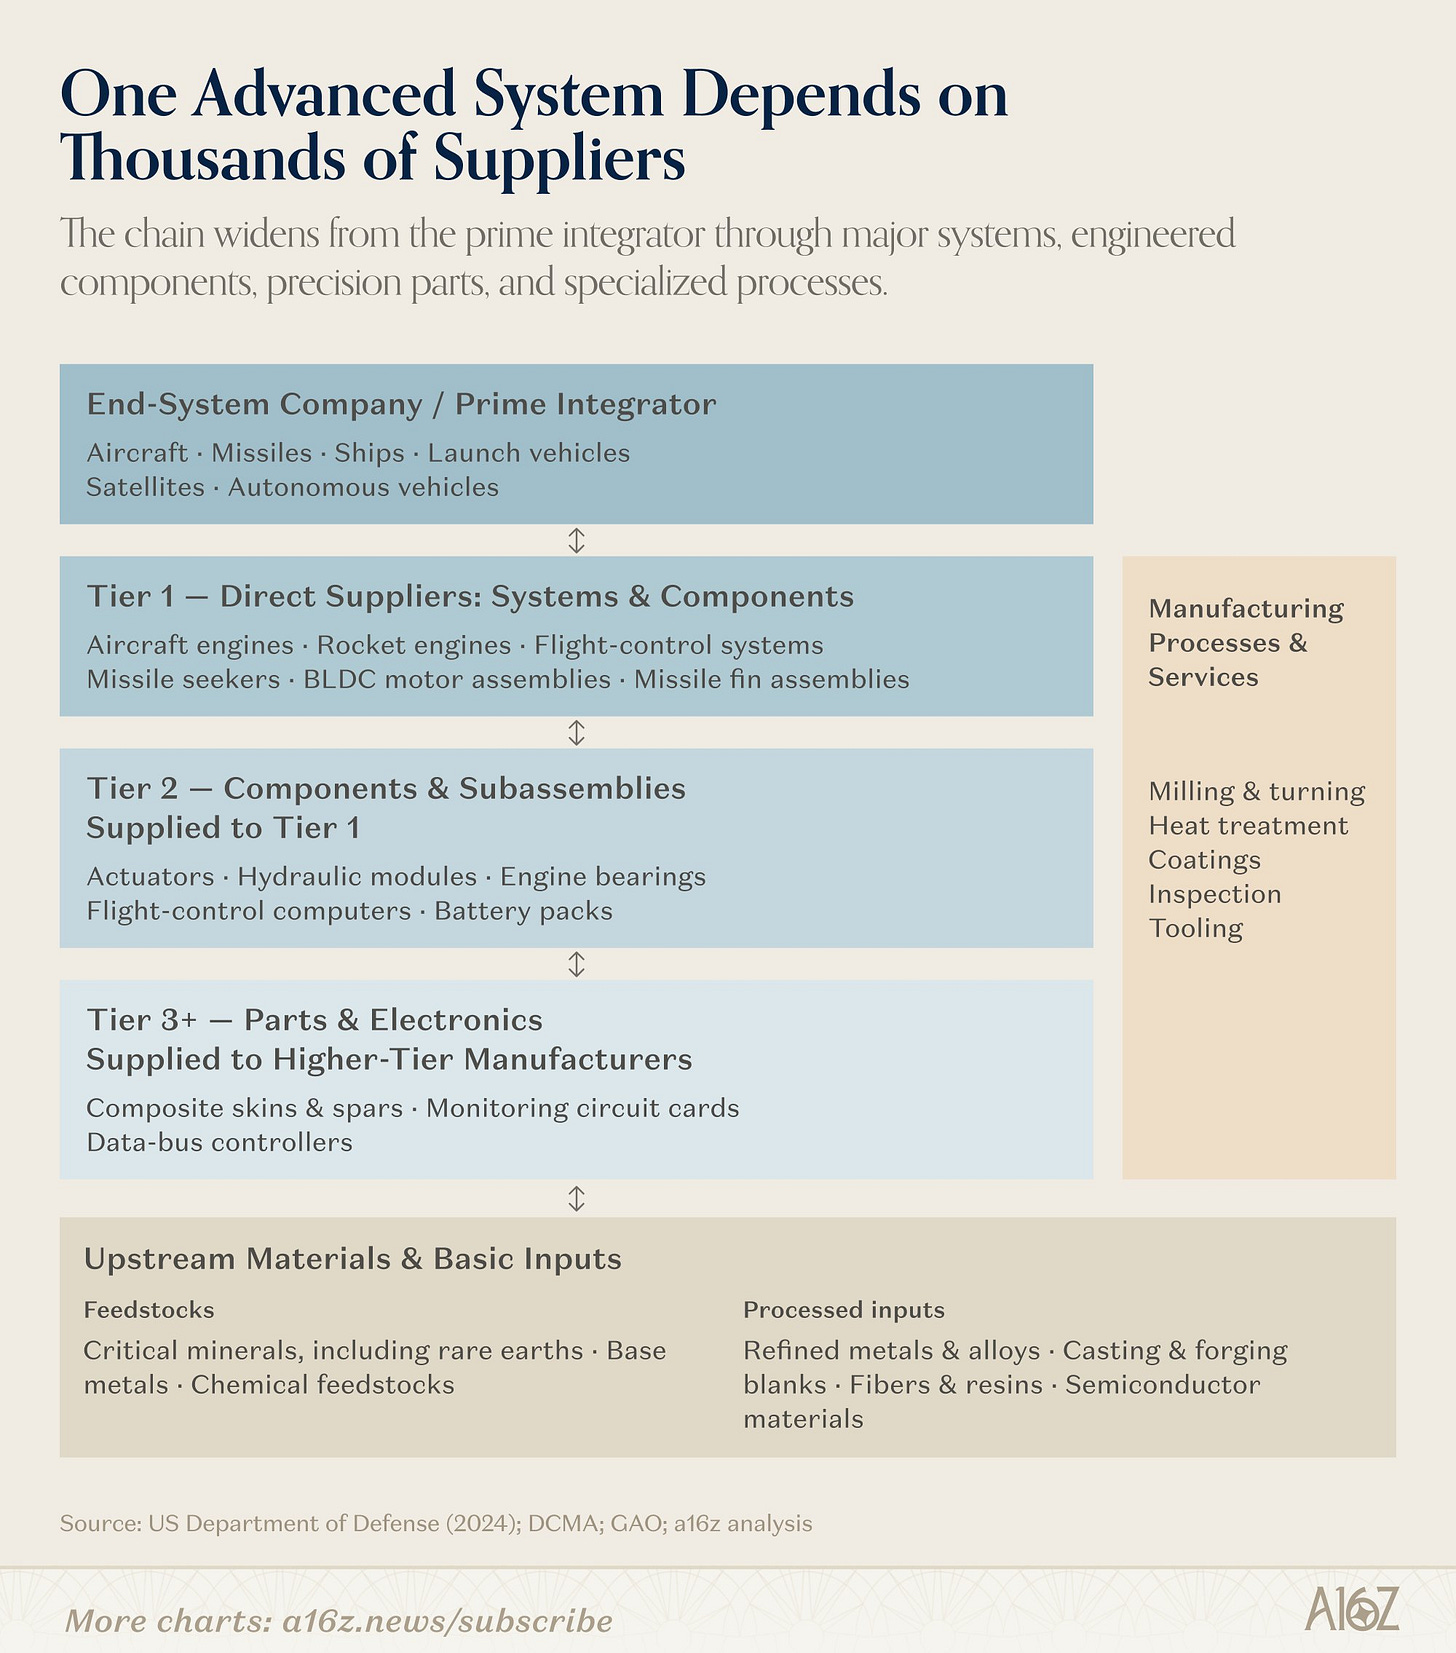
- In the wake of the current venture cycle centered around reindustrialization, Hadrian has emerged as one of the biggest winners in the race for capital. Just this August, the company raised $1.4B at an $8B valuation! A counterpoint from Alex Huckstepp is less a verdict than a question about the centralized model: should the future of manufacturing be a few giant, highly automated factories, or thousands of small, specialized shops made faster and better connected? While the idea of a factory capable of both high mix and high volume is memetic and fundable, the author argues it overlooks how much of American manufacturing operates and follows a lineage of similar failed centralized bets (see Katerra in construction, Zume in automated food production, and Plenty in vertical farming). Automation only pays off when production is standardized and repeatable, but much of American manufacturing work is high-mix. To be fair, Hadrian’s initial focus is on defense programs, where higher-volume, well-specified components are a good fit for automation. For the rest of the industry, the author points to how restaurants modernized as a model for distributed factories: software digitized and networked existing restaurants instead of replacing them (think Toast and DoorDash). We don’t need to build the factory of the future. We need to help the factories we have move like it’s the future.
- The answer to everything, apparently, is more compute and more data. For better or worse, we’ll find out how far the rabbit hole goes. Here are two recent collections of board designs and chip die shots to explore:
- HeyPCB’s Circuit World indexes KiCad projects from public GitHub repositories, including design files for The Open Book (an open-source e-book reader) and an ESP32-based Game Boy emulator. The intent is to make existing schematics and board layouts easier to discover and reuse.
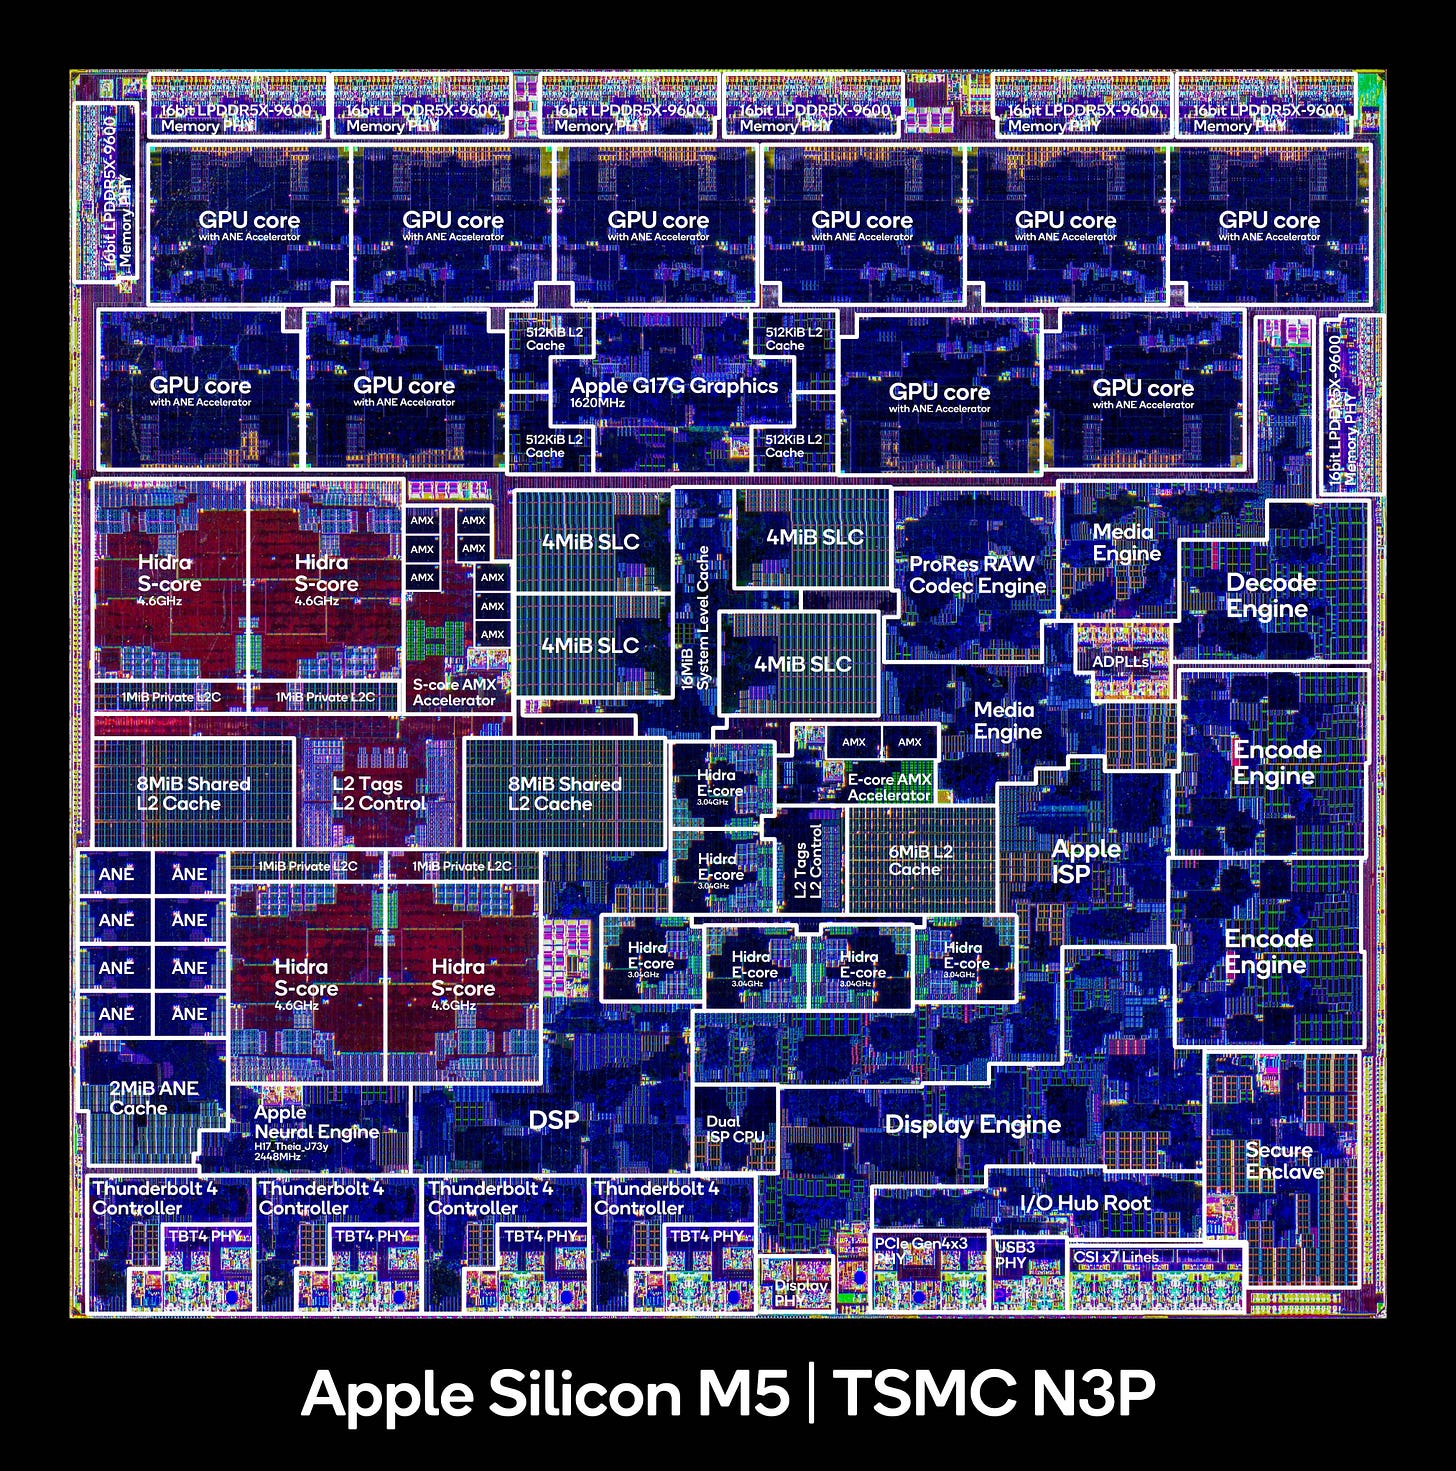
- HiEq’s die-shot gallery is a collection of annotated chip diagrams from Apple Silicon, Intel, AMD, and others. Consider it a visual reference for studying chip layouts and with some interpretation, comparing how different designs use their silicon area.
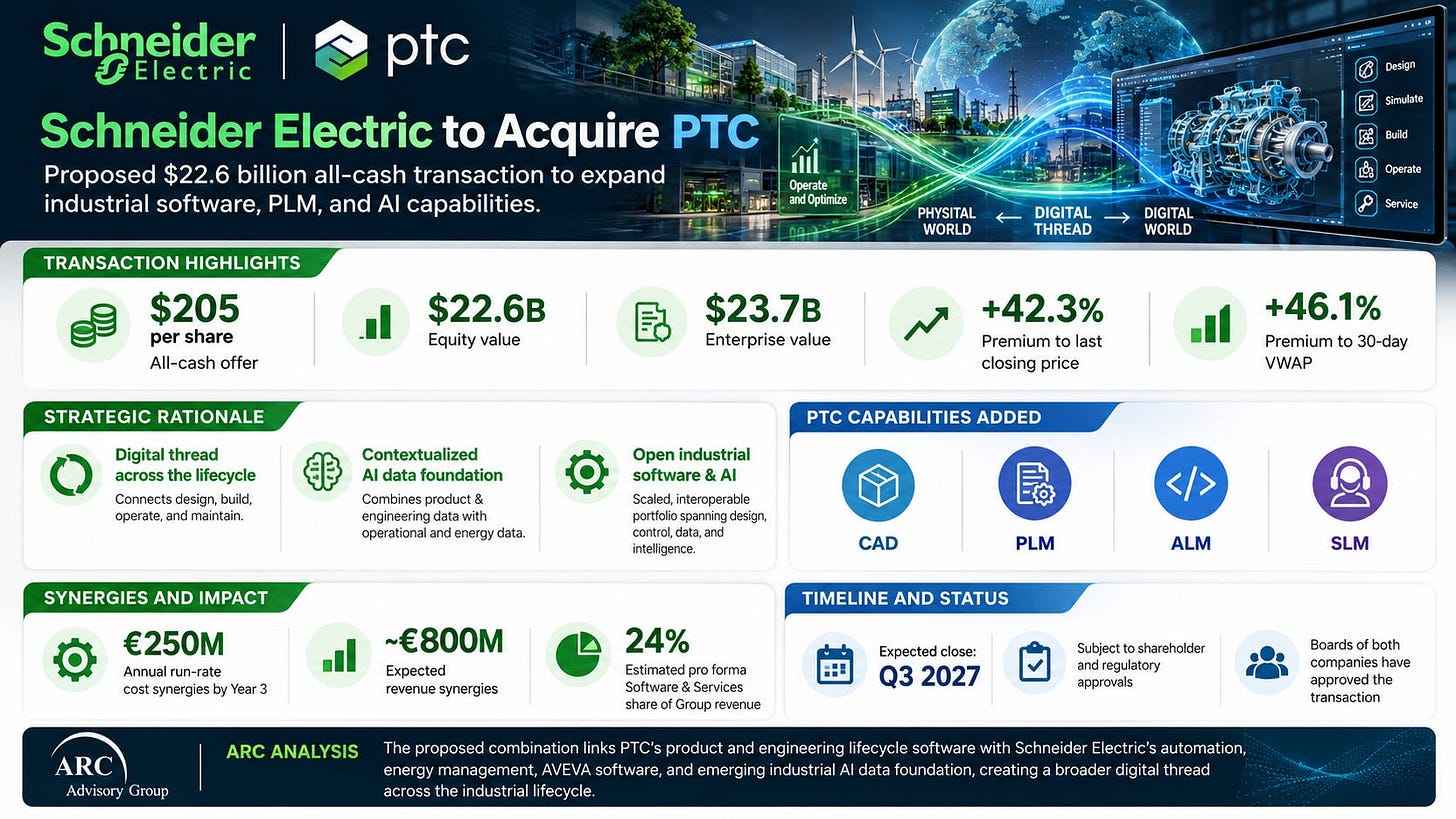
- The engineering CAD landscape is increasingly in the hands of industrial giants. Dassault has SolidWorks and CATIA, Siemens has NX and Solid Edge. Schneider Electric’s recent $22.6B deal for PTC now puts Onshape and Creo inside a French conglomerate best known for electrical equipment and factory automation. The broad rationale for Schneider is that pairing engineering and design data with its factory-floor systems will make its industrial AI offering more valuable. For PTC, the deal offers a 42% premium at a time when fears of AI disruption are weighing on software valuations. Max from Formlabs makes a guess at what the coming disruption of legacy CAD could entail: It will take a little while before AI really impacts their sales, but it will. I'd be surprised if 2 out of the 4 major CAD companies are not mostly dead in 5 years.
- Cadence has a great video series on analyzing PCBs and electrical schematics live, walking through the reasoning behind design decisions for a headphone pre-amplifier board. A useful resource for anyone connecting subsystems from different vendors or designing compact electronics. The hosts explain where to start when breaking down a design and what to look for in each group of components. Source files are available on Github.
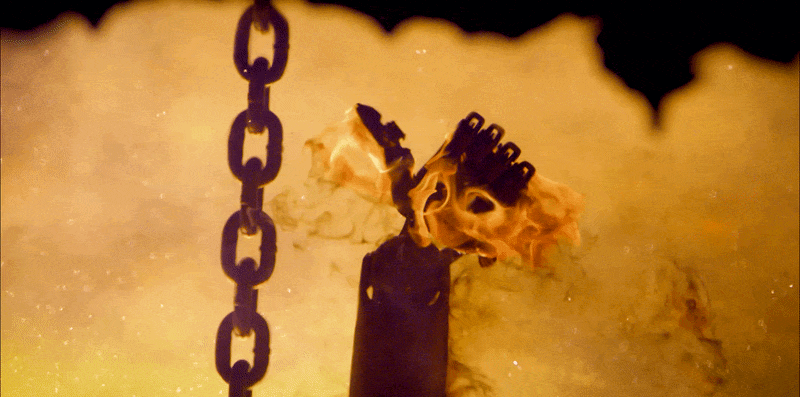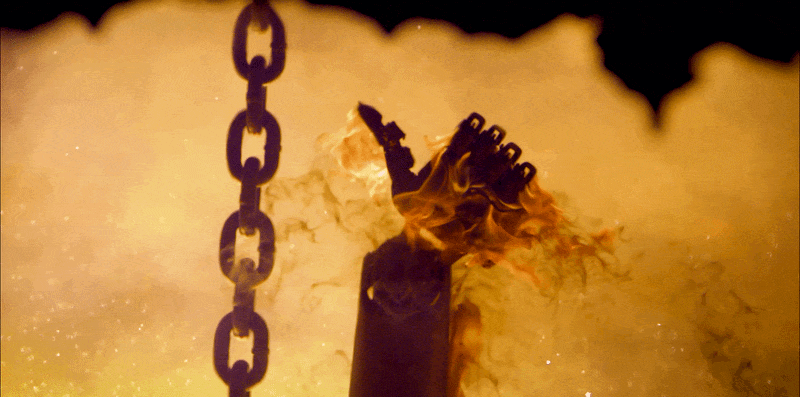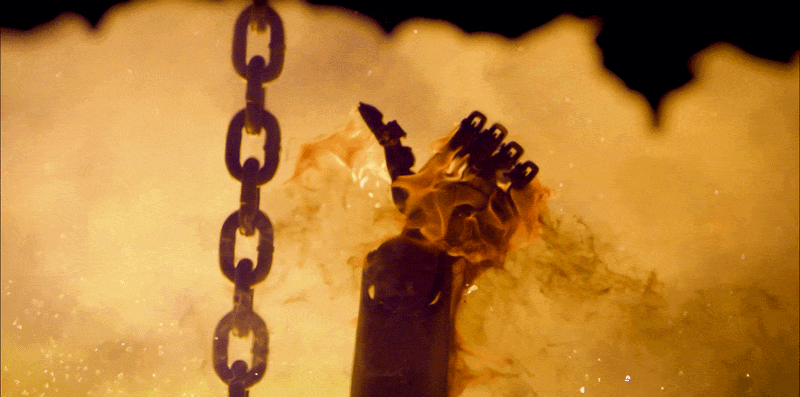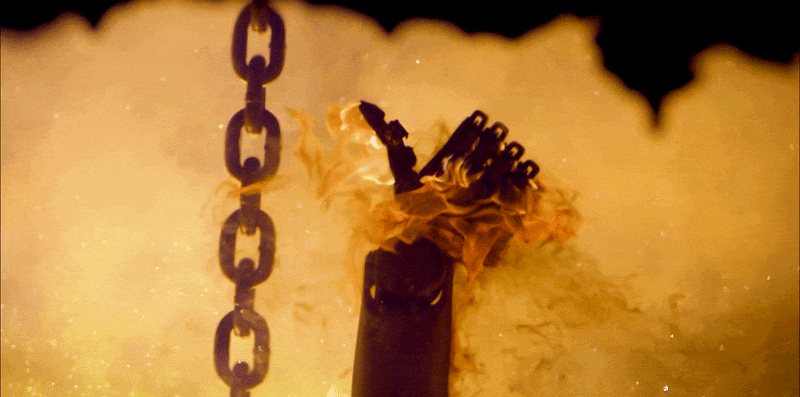
- And one fun link to round out the week: someone’s job at Figure was to train a subset of its F.02 fleet to jump into a steel furnace as part of a decommissioning stunt. For the unedited version, see Casey Schendel’s footage from the foundry. That’s me getting splashed with molten steel from a Figure F.02 jumping into a 75-ton electric furnace.
Startup News
- Flow Engineering raised a $50M Series B at a $750M valuation to develop its AI tools for hardware engineering and grow its engineering team. The software connects CAD drawings with product requirements, simulation results, and test data to help engineers track how design changes affect a system. The round was co-led by Valor Equity Partners and Atreides Management, with participation from Sequoia.
- Varda raised a $250M Series D to scale pharmaceutical manufacturing in orbit. The company builds capsules for drug development and manufacturing in microgravity, with re-entry flights also used for hypersonic testing. Government customers account for roughly 70% of Varda’s payload customer base for 2027, with commercial pharmaceutical work making up the rest. The round was led by Lux Capital and Natural Capital.
- Multiply Labs raised a $75M Series B to scale robotic drug manufacturing. The company builds robots that automate laboratory work used to produce gene therapies and mRNA treatments. Drugmakers purchase and operate the machines at their own facilities, with Multiply also selling cartridges, service, and support. Deployments are in the high single digits.
- Vinci raised a $250M Series B to expand its simulation software beyond semiconductors. The company started with thermal simulation for chips and plans to add system simulation, vibration testing, and electromagnetics.